Analytics Scientist – Dearborn, MI (Hybrid) | Visa + Salary Insights
📍 Location: us
🏷 Type: Not specified
Job Intelligence
📍 More in this location:
Browse AI jobs in us
🏷 Similar roles:
🌐 Explore all jobs:
View all AI job listings
Job Overview
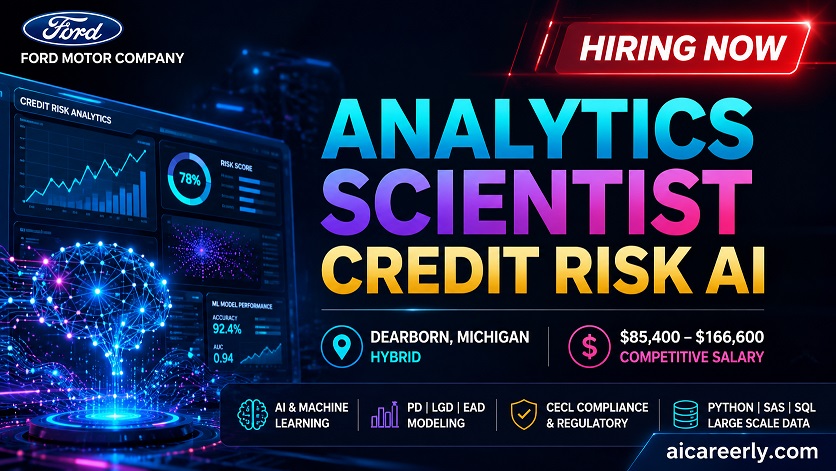
This role is for a highly quantitative Analytics Scientist focused on credit risk modeling within a major global automotive finance ecosystem at Ford Motor Company. The position sits inside Global Data Insight & Analytics and centers on developing advanced credit loss forecasting models including PD, LGD, and EAD. The ideal candidate is a strong statistician or data scientist with experience in financial modeling, machine learning, and large-scale data systems. This is a hybrid role requiring collaboration with finance, risk, and executive stakeholders to drive regulatory compliance and strategic decision-making.
📅 Job Timeline & Status
- 🟢 Job Posted: 11 May 2026
- ⏳ Application Deadline: 16 May 2026
- 🔄 Last Verified: 12 May 2026
- 📌 Hiring Status: Actively Hiring
- 🔥 Expected Response Time: 1–3 weeks (estimated)
This is in an early-to-mid hiring cycle, with a very short application window indicating structured intake and potentially high competition. Given the tight deadline and enterprise-level scope, candidates should apply immediately. Roles of this nature typically move fast due to regulatory and forecasting needs tied to credit risk operations.
🌍 Work Eligibility & Location
- 🌍 Visa Sponsorship: Available
- ✈️ Relocation Support: Not explicitly stated (likely available for senior quantitative hires)
- 🏠 Remote Type: Hybrid (4+ days onsite expected near Dearborn hub)
- ⏰ Timezone Requirement: US Eastern Time alignment preferred
- 🌐 Country Restrictions: Must be authorized to work in the United States
- 🗣️ Language Requirement: English
This role is primarily US-based with strict work authorization requirements, but visa sponsorship is explicitly available, making it accessible for strong international quantitative talent. However, hybrid onsite expectations significantly reduce full-remote flexibility.
💰 Salary Intelligence
- 💰 Official Salary: $85,400 – $166,600
- 📊 Estimated Range: $95K – $160K typical placement band
- 📈 Level: Mid-Level to Senior-Level (Grade 6–7)
This is a highly competitive compensation structure for a credit risk analytics role. The upper band aligns with senior-level quantitative modelers with production-grade experience in regulatory frameworks. Total compensation value increases significantly with bonus eligibility and enterprise benefits.
📊 Role Breakdown
This position focuses on building and maintaining advanced credit risk models that directly influence lending decisions, capital planning, and regulatory reporting. You will work with large-scale financial datasets, combining structured credit performance data with macroeconomic indicators. A major part of the role involves designing Probability of Default (PD), Loss Given Default (LGD), and Exposure at Default (EAD) models using both classical statistical techniques and modern machine learning pipelines.
Expect to work heavily in Python, SAS, and SQL for data extraction, transformation, and modeling workflows. Time-series forecasting, survival analysis, and multivariate regression are core techniques used to evaluate portfolio behavior over time. Approximately 40–50% of the role involves model development, while another 30% focuses on validation, monitoring, and governance compliance under regulatory frameworks like CECL.
The remaining portion involves stakeholder communication—translating complex quantitative outputs into actionable business insights for finance leadership. You will also support stress testing scenarios, portfolio risk simulations, and macroeconomic sensitivity analysis.
🧩 Required Skills & Fit
- ✅ Must: Master’s in Statistics, Math, Data Science, or related field
- ✅ Must: Strong experience in credit risk or financial modeling
- ✅ Must: Proficiency in Python, SAS, or R
- ➕ Bonus: PhD in quantitative discipline
- ➕ Bonus: Machine learning deployment experience
📈 Difficulty & Competitiveness
- ⚡ Level: High
- 📊 Experience barrier: 3–7 years preferred
- 🧠 Skill complexity: Advanced statistical + ML + regulatory modeling
- 🌍 Competition: High (global finance + AI talent pool)
This is a technically demanding role requiring strong mathematical foundations and applied financial modeling expertise. Competition is intense due to the combination of strong brand value, visa sponsorship, and high compensation ceiling.
🚀 Career Impact
- ⭐ Impact Rating: ⭐⭐⭐⭐⭐
- 🏢 Brand value: Global automotive + financial institution
- 📚 Skill growth: Advanced credit risk + ML modeling
- 🚀 Future opportunities: Quant finance, AI risk leadership, fintech strategy
This role significantly strengthens expertise in regulated AI systems, credit modeling, and enterprise-scale analytics. It positions candidates for future leadership roles in risk analytics, financial AI systems, and quantitative strategy domains.
📋 Key Responsibilities
You will design, validate, and deploy advanced statistical models supporting enterprise credit forecasting. Core responsibilities include building PD, LGD, and EAD models using Python, SAS, and machine learning frameworks. You will analyze large-scale credit datasets, integrate macroeconomic variables, and perform scenario-based stress testing.
A critical function is maintaining model governance compliance under CECL regulatory requirements, ensuring models are both explainable and auditable. You will also collaborate with cross-functional teams including risk, accounting, and finance to translate quantitative outputs into business decisions.
Additional duties include portfolio monitoring, ad-hoc risk analysis, and continuous model improvement using performance diagnostics and back-testing methodologies.
🎯 Application Strategy
- 🎯 Best apply method: Direct company career portal submission
- 🔥 Highlight: Credit risk modeling experience
- 🔥 Highlight: Python + SAS + SQL proficiency
- ❌ Avoid: Generic data science framing without finance context
- ❌ Avoid: Weak explanation of regulatory exposure
🧠 Application Optimization (Adaptive)
This section is personalized by seniority.
How to use: Paste into ChatGPT, Claude, or Gemini
Analytics Scientist focused on credit risk modeling (PD, LGD, EAD), machine learning, and regulatory compliance within an automotive financial ecosystem.
Candidate:
[Paste CV]
Optimize for this role.
Focus:
Signal strength
Credit risk alignment
Modeling depth
Regulatory exposure
Missing high-impact elements
🧠 Fit & Positioning Analysis
Evaluate your alignment carefully before applying.
Match score
Strengths in statistical modeling
Gaps in credit risk or regulatory experience
Positioning improvements for enterprise finance analytics roles
📅 Application Signals
This role shows high urgency due to a short application window and enterprise-level risk requirements. Competition is expected to be strong, especially from candidates in quantitative finance and AI-driven analytics backgrounds. Because the deadline is tight and structured, interview cycles are likely fast-moving.
Urgency is high, competition is global, and shortlisted candidates may be contacted quickly within days of submission. If applying, immediate action is strongly recommended. Applications may close without notice if sufficient candidate volume is reached.
🚀 Resume Optimization for This Role
⚡ Takes less than 2 minutes — optimize specifically for this position before applying
🎯 0/5 completed
Tailoring your CV to this exact role significantly increases your chances.
✅ Ready to apply — your profile is aligned with this role
🔗 Apply for this Job
✅ Job Source & Verification
This listing is based on an official posting from Ford Motor Company careers portal, a globally recognized employer in automotive and financial services analytics. Data was last reviewed on 12 May 2026, with posting verified against the original job description. All salary, role scope, and eligibility details align with enterprise-grade credit risk analytics hiring standards.
Similar Jobs
Staff Software Developer, AI/ML Safety & Security – Waterloo / New York / Sunnyvale | Visa + Salary Insights
Location: ca, us
Type: Full-time
Hardcore Engineer (All Levels) – Remote (Global Regions) | Visa + Salary Insights
Location: ae, Africa, au, ca, eu, gb, jp, nl, Others, us
Type: Full-time

Senior Backend Engineer, AI Security – San Francisco / Seattle / Remote (US & Canada) | Visa + Salary Insights
Location: ca, us
Type: Full-time

Applied Machine Learning Scientist – North America Remote | Visa + Salary Insights
Location: ca, us
Type: Full-time